020 7898 0500
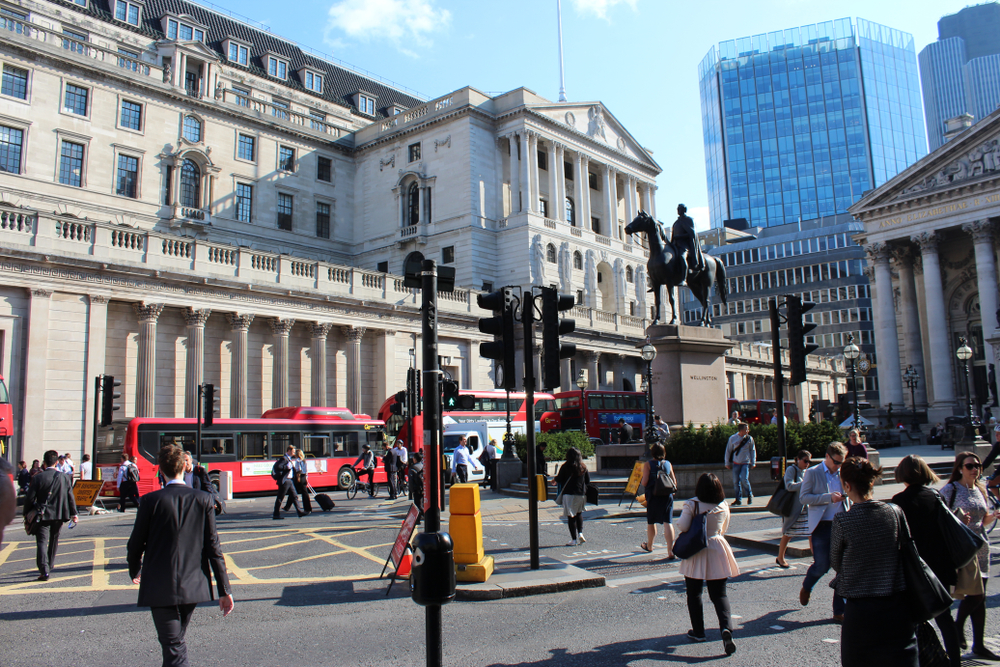
A busy time for the Bank of England, and for London shoppers too (Alan Kean / Shutterstock.com)
Sterling lost some ground to both the euro and US dollar yesterday after the Bank of England (BoE) held its interest rate, despite rising inflation, oil still being above $100 per barrel and, we hear this morning, a rise in retail sales.
The BoE’s decision to hold (by a six to three vote again by its committee) was widely predicted but came despite the European Central Bank (ECB) and US Federal Reserve (‘The Fed’) raising interest rates in the latest round. For the Fed that was the first rise since 2023. In a statement the BoE’s policymakers said they did not see that oil price rises were feeding through into “secondary effects”, i.e. other prices and indeed wage rises.
Still, for British retirees the way is now clear for a 3.9% pension increase next year, based on average wage rises this year and the triple lock. Good news for retirees in the eurozone particularly, where inflation is generally lower.
The difference in return for investors between the UK and US has been immediately felt in exchange rates, and the pound is more than 1% weaker against the dollar than this time last week. Indeed, GBP/USD is at its weakest since late July.
GBP/EUR is also down, to around its weakest since early July, but remains more than 1% stronger than the levels it was becalmed at for much of the past year.
This morning the Office for National Statistics (ONS) revealed that British shoppers spent around 0.5% more in August, reversing July’s fall. Sales were also 2.4% higher than a year ago, with online retailers and department stores helping to drive the recovery.
There are also signs that higher prices are changing behaviour. Fuel sales fell in August as prices rose sharply, with retailers reporting that motorists were making smaller fill-ups at the pumps. That leaves the UK with a familiar balancing act: consumer spending is proving fairly resilient, but the energy shock continues to squeeze household budgets and keep inflation elevated.
Next week shifts the focus away from central bank meetings and back towards the health of the economy. Wednesday brings the latest flash Purchasing Managers’ Index (PMI) readings from the UK, eurozone and United States. Those surveys should give markets an early look at how businesses are coping with higher energy prices and borrowing costs.
GBP: Shoppers steady the mood
The pound has been steady in early trading this morning after slipping against both the euro and US dollar yesterday. This morning’s retail sales figures offered a more encouraging domestic signal, with August’s rebound showing that households have not completely shut their wallets despite higher prices. Next week’s UK PMI figures will offer the next important test of that balance. We then start a fallow period for data where the spotlight is likely to fall on the Autumn Budget.GBP/USD: the past year
EUR: Euro holds its ground
The euro gained some ground against sterling yesterday and recovered slightly against the US dollar following the sharp moves around Wednesday’s Federal Reserve meeting. Following the ECB’s interest rate increase last week, the question now is how well the eurozone economy absorbs those higher borrowing costs. Wednesday’s flash PMI readings will be closely watched for signs that businesses are weathering the combination of higher energy bills and tighter monetary policy.GBP/EUR: the past year
USD: Dollar hangs on to Fed gains
The US dollar has retained most of the ground it won following Wednesday’s interest rate increase. That move was helped by evidence that the American consumer remains in decent shape, with US retail sales having jumped sharply in August by 1.2% and certainly putting the UK’s 0.5% in the shade. The focus now moves from what the Fed has done to whether the economy can justify further tightening. Next week’s US PMI readings will add another piece to that puzzle and give markets a fresh look at business activity after a turbulent few weeks for interest-rate expectations.USD/GBP: the past year
For more on currencies and currency risk management strategies, please get in touch with your Smart Currency Business account manager on 020 3918 7255 or your Private Client account manager on 020 7898 0541.